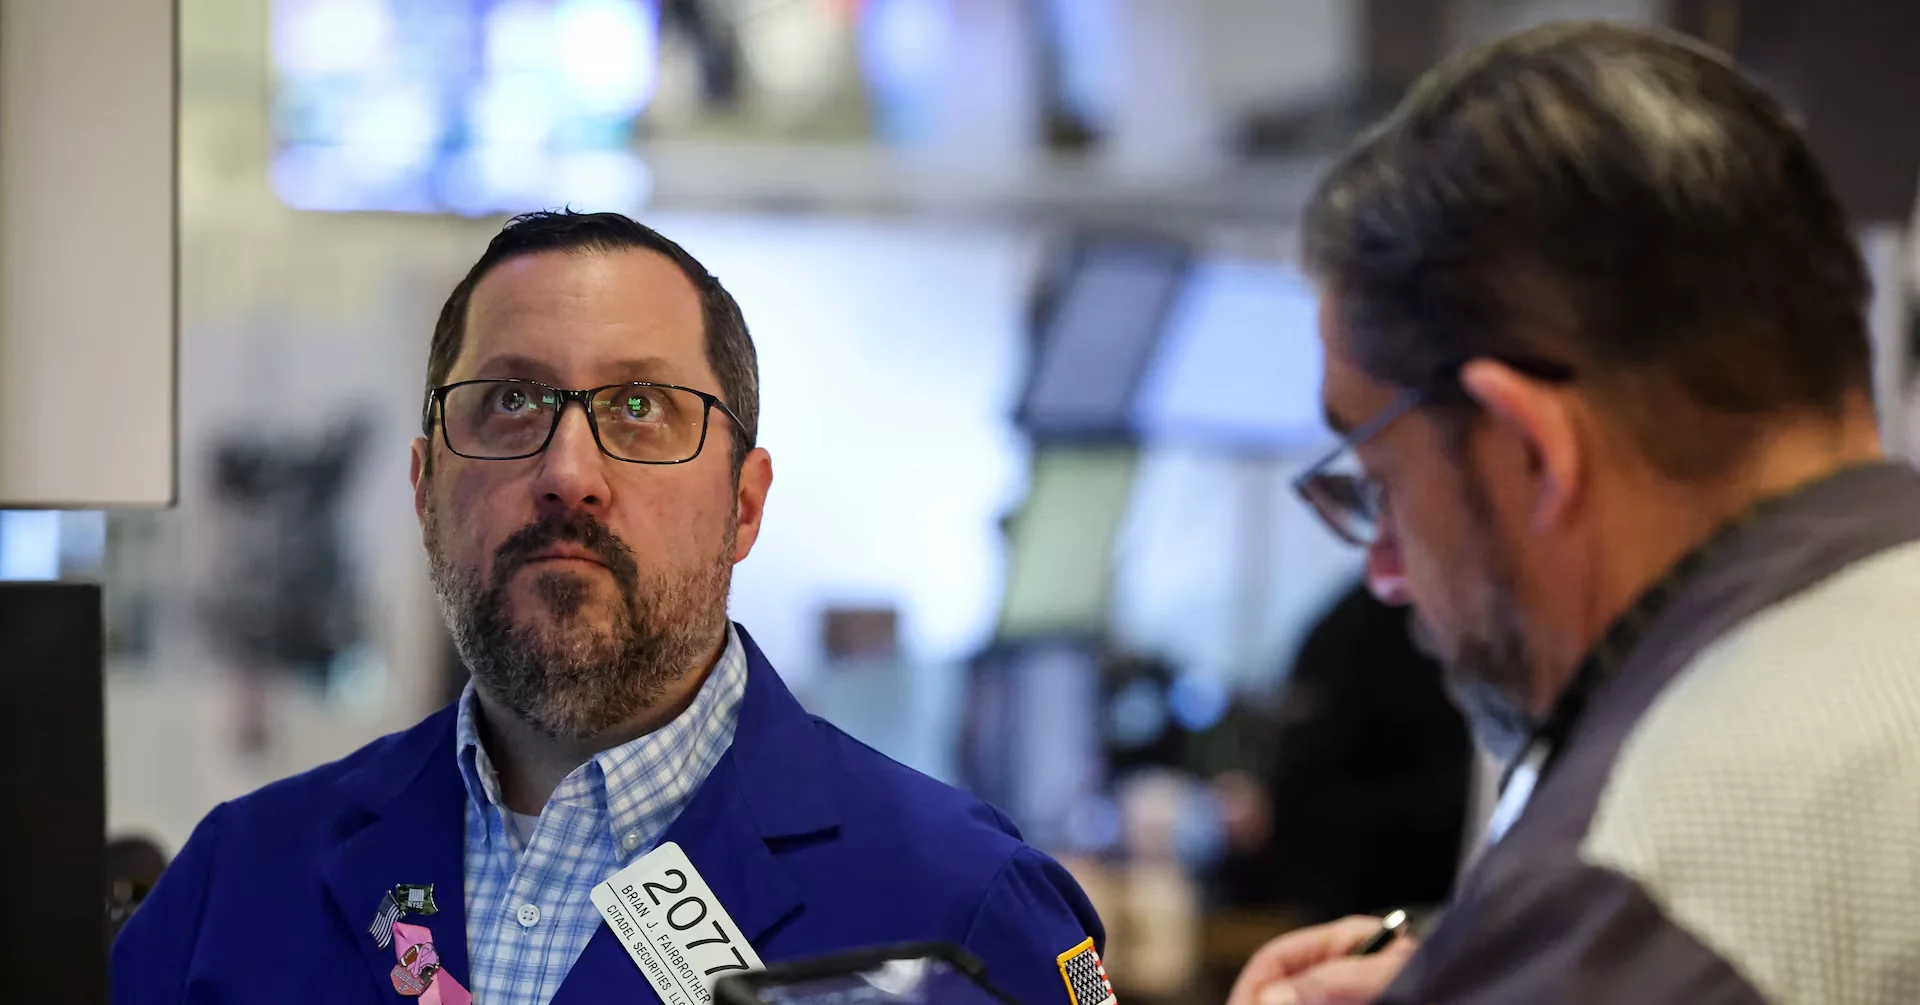
United States equity markets staged an explosive broad-based rally on Monday, decisively breaking a multi-week slump as plunging energy commodities and solid macroeconomic fundamentals sparked aggressive dip-buying across all major exchanges. The Dow Jones Industrial Average surged 1,104.20 points, or 2.16 percent, to finish the trading day at 52,394.36, marking its strongest single-session point advance of the year.
The broader market participated fully in the upside momentum. The benchmark S&P 500 climbed 172.97 points, or 2.34 percent, to settle at 7,549.83, while the tech-heavy Nasdaq Composite jumped 671.13 points, or 2.73 percent, to close at 25,250.55. Every single one of the S&P 500’s eleven primary industry sectors finished in positive territory, with consumer cyclicals, industrial manufacturers, transport logistics, and enterprise software leading the advance.
Market analysts attributed the sharp turnaround to a steep decline in global energy prices. West Texas Intermediate (WTI) crude futures dropped below $86 per barrel after diplomatic communications from Gulf capitals suggested that direct military blockades near the Strait of Hormuz were being averted. The sudden drop in oil prices provided immediate relief to investors who had feared an energy-induced resurgence in headline inflation.
Easing Inflation Worries Clear Path for Consumer and Tech Gains
The pullback in energy costs arrived ahead of critical economic indicators scheduled for release later this week, most notably the October Consumer Price Index (CPI) report. Lower fuel and transport expenses are expected to reinforce disinflationary trends, giving the Federal Reserve greater latitude to maintain an accommodative monetary posture as policymakers deliberate rate strategy heading into their final meeting of 2026.
"What markets witnessed today was a classic relief rally coupled with powerful macroeconomic validation," explained Sarah Henderson, chief investment strategist at Manhattan Global Partners. "When crude oil prices plummeted from six-month peaks, it instantly dismantled the stagflation narrative that had weighed down institutional sentiment over the preceding two weeks. Investors realized that the underlying domestic economy remains remarkably resilient."
Consumer discretionary giants posted some of the day’s most impressive gains. Retail leaders like Amazon and Walmart advanced more than three percent, buoyed by expectations of robust holiday spending. Industrial powerhouses such as Caterpillar and Boeing also surged as supply chain logistics stabilized and transport cost projections were revised lower.
Semiconductors Shrug Off Nvidia Governance Drag
The technology sector exhibited notable resilience during Monday’s trading. While Nvidia shares slipped roughly 4.5 percent following revelations of an internal corporate governance investigation into CEO Jensen Huang, the broader semiconductor industry shrugged off the single-company drag. Key chip equipment suppliers and rival processor manufacturers gained between two and five percent as institutional funds rotated capital across the artificial intelligence infrastructure landscape.
Treasury yields also eased across the yield curve, with the benchmark 10-year Treasury yield slipping four basis points to 4.18 percent, down from recent monthly highs. The retreat in yields provided an additional catalyst for high-growth tech firms and regional banks.
As trading volume exceeded the thirty-day moving average, market strategists noted that institutional cash reserves that had sat on the sidelines during the volatile midterm election cycle are now seeking deployment. With corporate earnings season wrapping up with better-than-expected profit margins, Wall Street appears well positioned to carry positive momentum into the year-end trading cycle.